OpenAI's Wallet lets ChatGPT spend your money – a risky leap
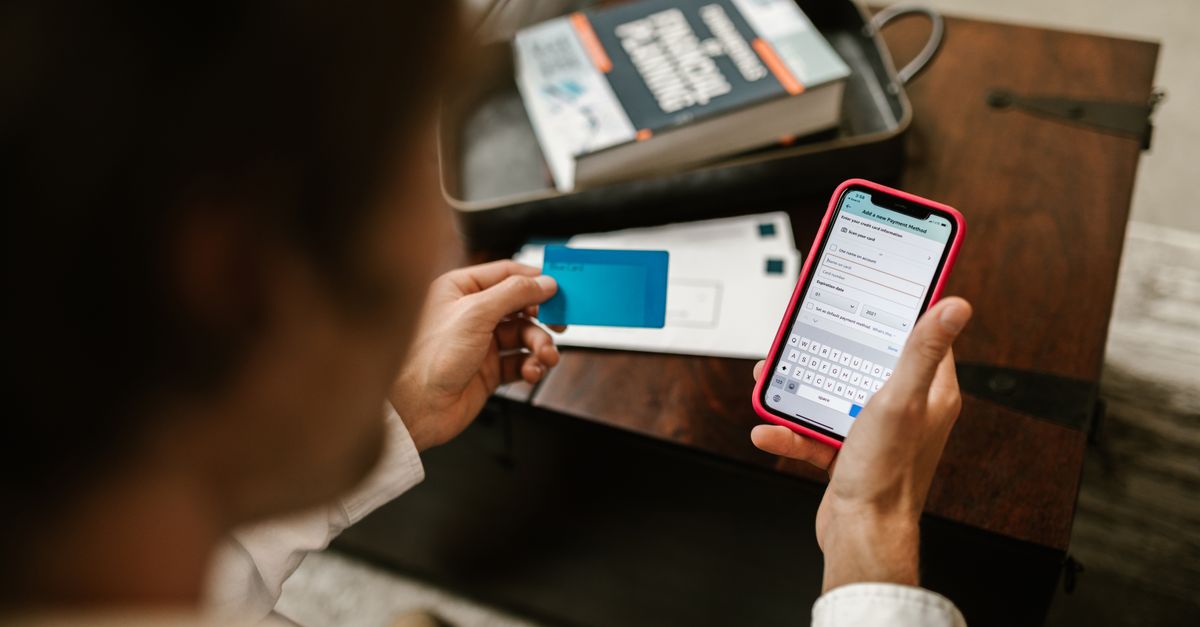
Photo by RDNE Stock project on Pexels
OpenAI rolls out a Wallet that can buy for you
OpenAI’s new Wallet feature lets ChatGPT place orders using the user’s payment data.12345678 The move turns a conversational assistant into a checkout clerk.
Engadget reports that the feature enables AI agents to make purchases on a user’s behalf once the user links a bank account or card.12345678 No other details are provided, but the headline alone forces engineers to wonder how token‑level security will survive in a world where prompts can trigger real‑world transactions.
How the feature actually works
The rollout is limited to ChatGPT Plus subscribers, according to the Engadget piece.235678 Users must opt‑in, attach a payment method, and then invoke a purchase command such as “order a new phone plan.”2345678 The AI then contacts the merchant, fills the cart, and confirms the transaction.245678
Because the feature lives inside the same cloud environment that powers the language model, the same API keys that generate text also carry payment credentials. That conflation of conversational and financial APIs is unprecedented in consumer‑facing AI.
Privacy and security concerns surface instantly
Giving an LLM unfettered access to a bank account feels like handing a stranger the keys to your house and asking them to water the plants. The Engadget article does not detail any safeguards beyond a user‑enabled toggle, so the engineering community is left to speculate.
OpenAI has a history of releasing powerful tools without exhaustive audits. The Wallet adds a new attack surface: a malicious prompt could be crafted to siphon funds, or a compromised model could be tricked into spending on a hidden subscription. Regulators in the EU and the US have already warned that AI‑driven financial services must meet the same standards as traditional fintech, but no official guidance has been published yet.
Black Friday deals highlight why people might trust an AI checkout
While OpenAI is busy turning chat into commerce, retailers are slashing prices across the board. 9to5Google notes that a new phone plan can be secured for as little as $6.50 per month during Black Friday. Nothing’s headphones and phones are also seeing discounts up to 45 % and $400 respectively. Meta’s Quest 3S doorbuster bundles a $50 Best Buy gift card with the headset.
These deep discounts create a sense of urgency that aligns with the Wallet’s promise: “just tell me what you want, and I’ll buy it.” For a consumer juggling multiple low‑cost plans and hardware deals, the convenience of a hands‑free checkout might outweigh the perceived risk—especially when the alternative is manually hunting coupon codes.
Industry context: AI agents entering the fintech arena
OpenAI is not the first player to experiment with AI‑driven purchases. Smaller startups have offered “shopping bots” that scrape product pages and auto‑fill checkout forms. However, those bots operate in a narrow, rule‑based fashion. By embedding purchasing logic directly in a large language model, OpenAI blurs the line between recommendation and execution.
The move also forces traditional fintech firms to confront a new competitor that does not need a banking license to initiate transactions—only a cloud account and a user’s consent. If the Wallet gains traction, banks may need to build API layers that can verify AI‑generated requests in real time, a capability most current open‑banking standards lack.
What to watch
Track OpenAI’s next transparency report for data on how many Wallet transactions occur and what fraud rates look like. Regulators are expected to release guidance on AI‑enabled payments by early 2025; that will set the compliance baseline for any LLM that can move money. Finally, watch how retailers respond—will they embed AI checkout widgets of their own, or will they ban third‑party agents from accessing their carts? The answer will shape the next wave of consumer‑AI interaction.
Footnotes
Related Articles
OpenAI’s Apple flop
OpenAI reports weak uptake of ChatGPT in Apple Intelligence, rolls out voice mode upgrades, and faces two high‑profile security incidents in Australia.
Meta’s Hatch, OpenAI’s Astra
Meta rolls out internal AI agent Hatch, OpenAI unveils Astra’s new reasoning method, and a lawsuit forces a look at secret AI safety rules.
OpenAI adds business profiles as ChatGPT edges toward search
OpenAI rolls out business profiles to turn ChatGPT into a consumer discovery tool, while rivals push hardware tracking and AI assistants.